What the GST Council recommended on 8 October 2026
What the GST Council recommended on 8 October 2026
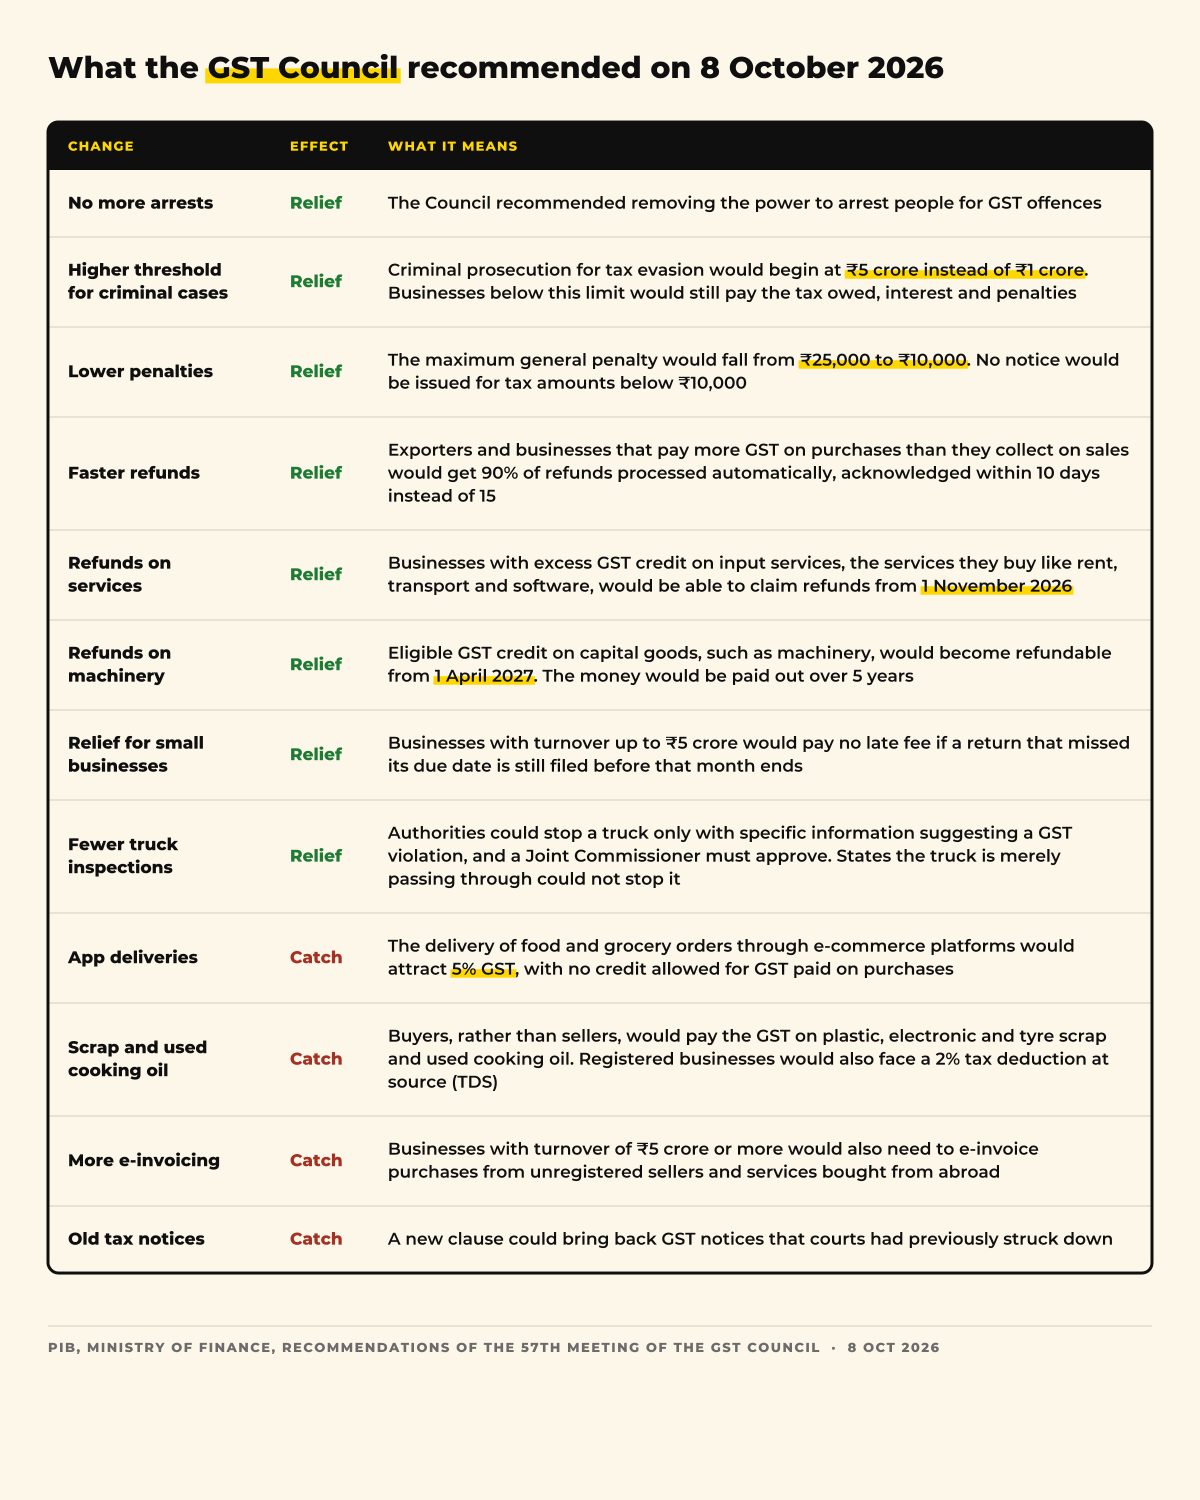
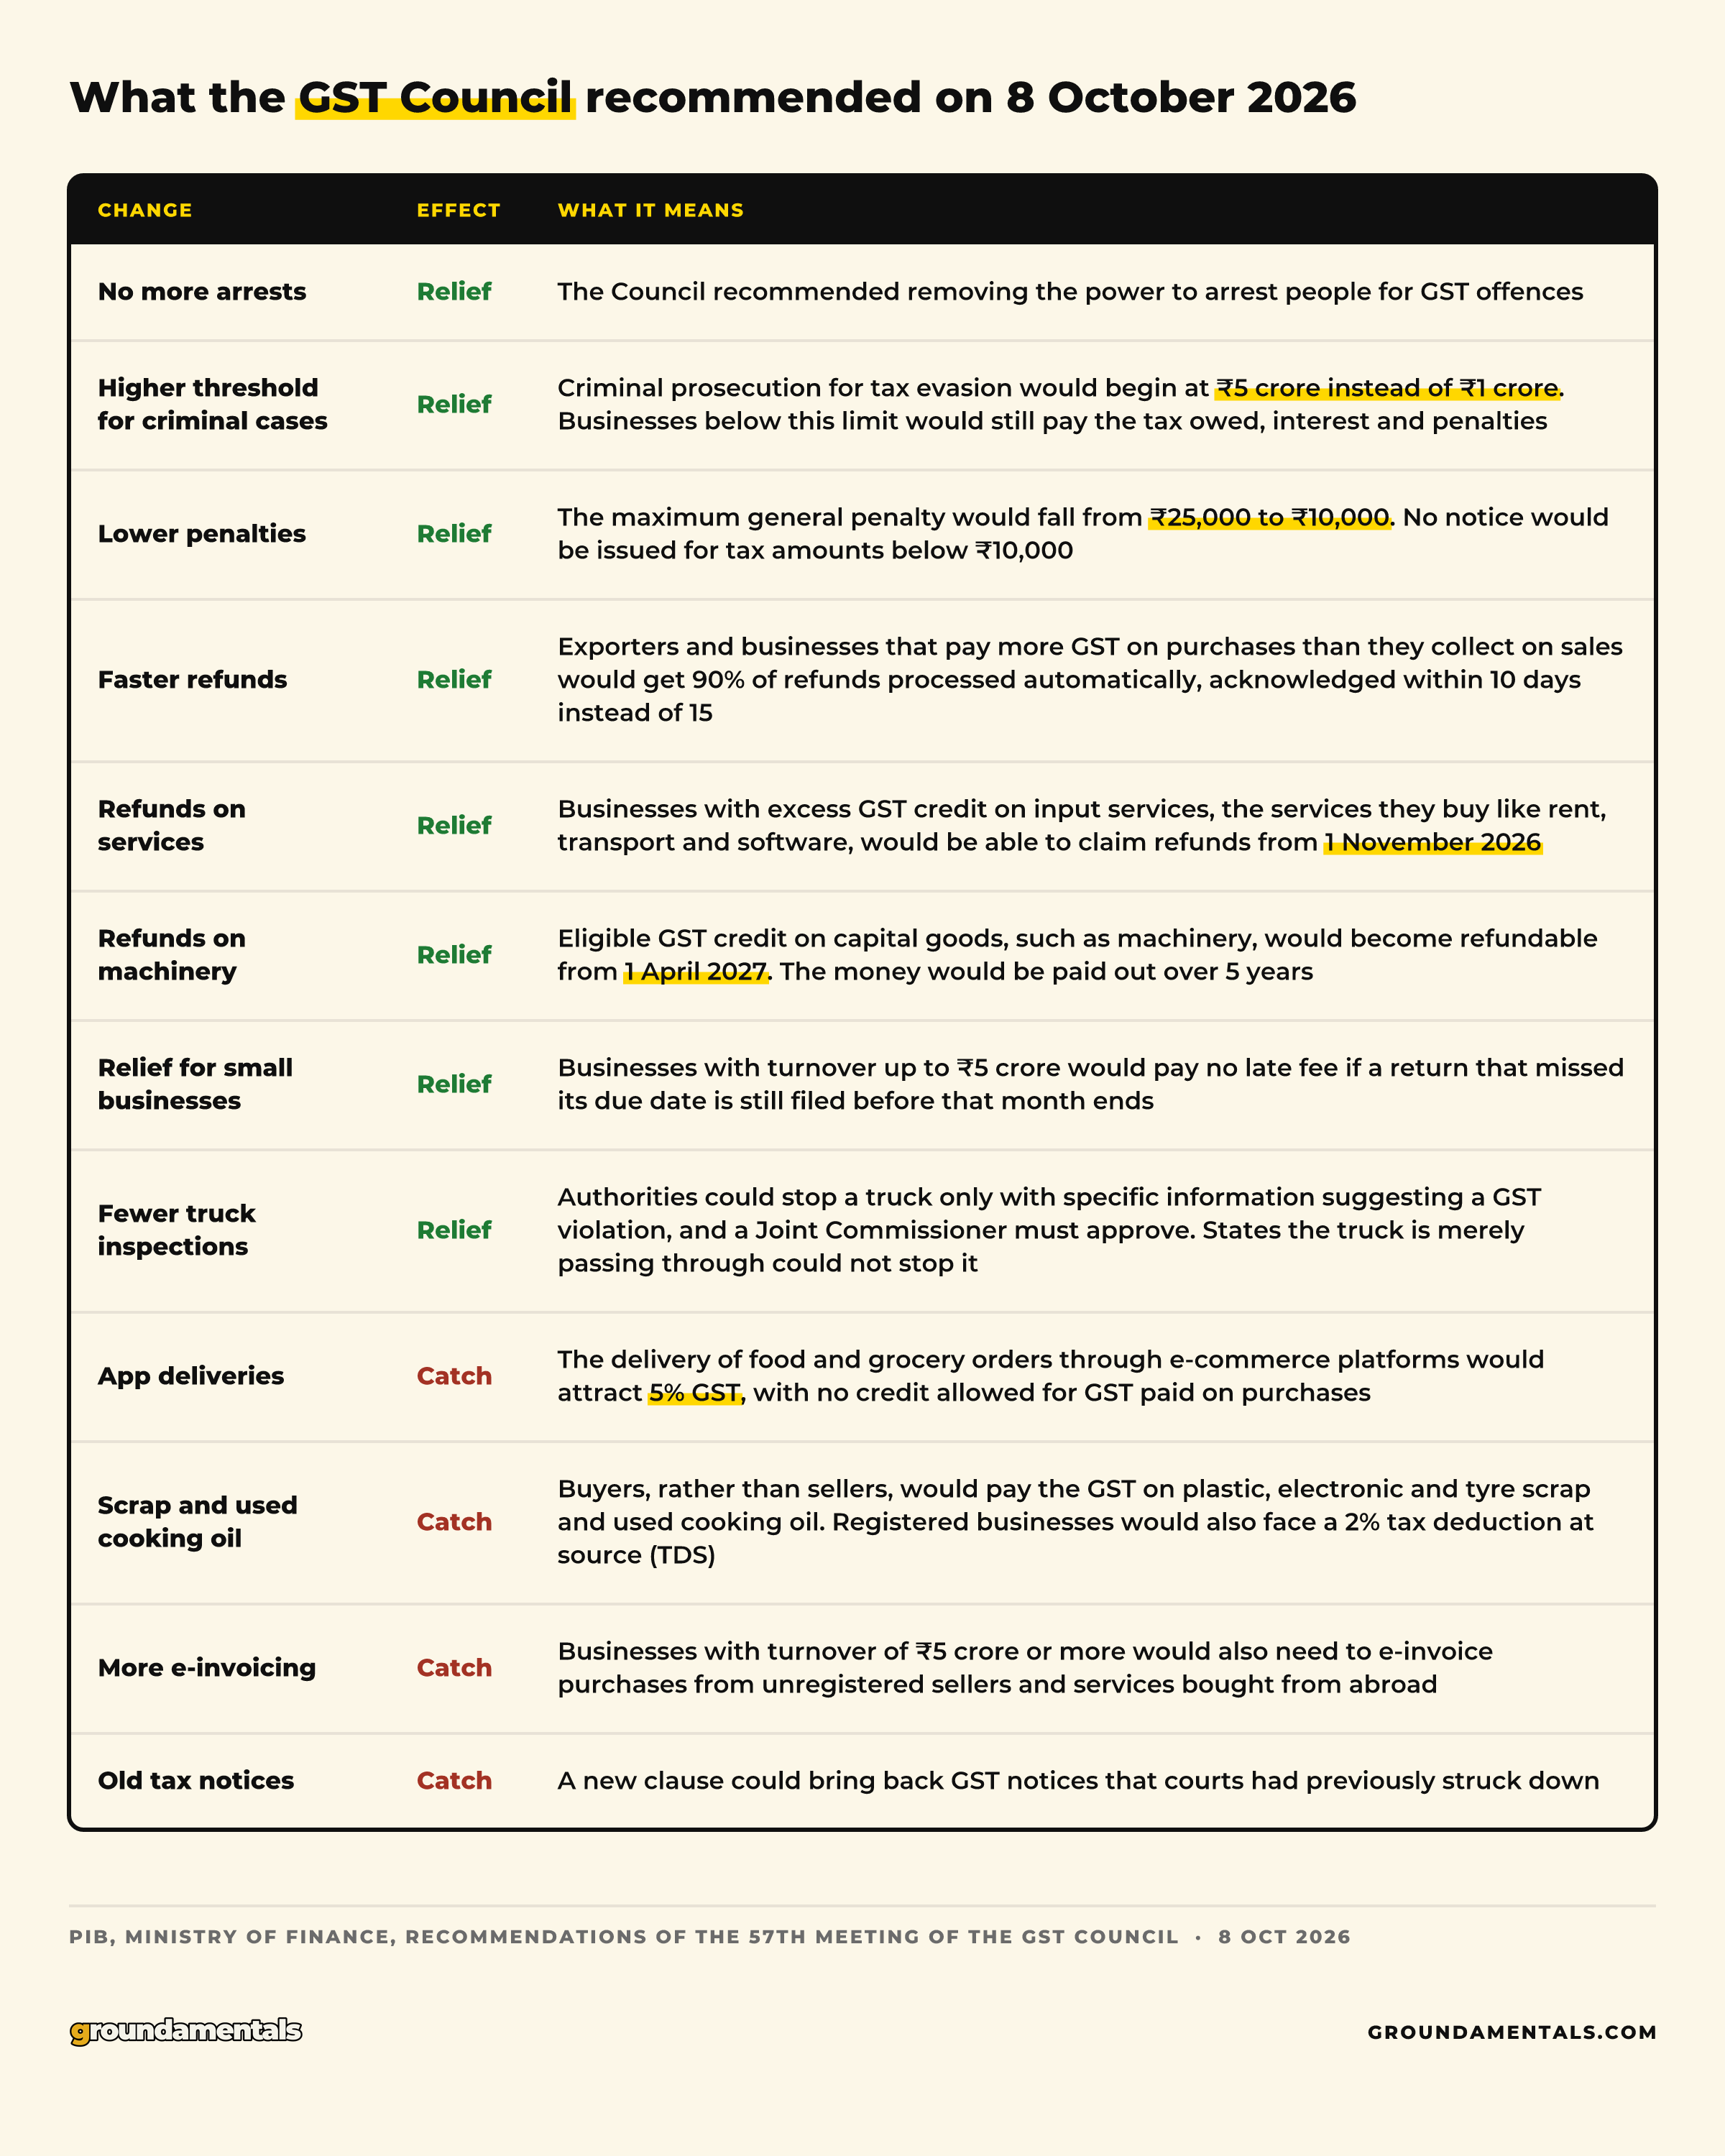
| Change | Effect | What it means |
|---|---|---|
| No more arrests | Relief | The Council recommended removing the power to arrest people for GST offences |
| Higher threshold for criminal cases | Relief | Criminal prosecution for tax evasion would begin at ₹5 crore instead of ₹1 crore. Businesses below this limit would still pay the tax owed, interest and penalties |
| Lower penalties | Relief | The maximum general penalty would fall from ₹25,000 to ₹10,000. No notice would be issued for tax amounts below ₹10,000 |
| Faster refunds | Relief | Exporters and businesses that pay more GST on purchases than they collect on sales would get 90% of refunds processed automatically, acknowledged within 10 days instead of 15 |
| Refunds on services | Relief | Businesses with excess GST credit on input services, the services they buy like rent, transport and software, would be able to claim refunds from 1 November 2026 |
| Refunds on machinery | Relief | Eligible GST credit on capital goods, such as machinery, would become refundable from 1 April 2027. The money would be paid out over 5 years |
| Relief for small businesses | Relief | Businesses with turnover up to ₹5 crore would pay no late fee if a return that missed its due date is still filed before that month ends |
| Fewer truck inspections | Relief | Authorities could stop a truck only with specific information suggesting a GST violation, and a Joint Commissioner must approve. States the truck is merely passing through could not stop it |
| App deliveries | Catch | The delivery of food and grocery orders through e-commerce platforms would attract 5% GST, with no credit allowed for GST paid on purchases |
| Scrap and used cooking oil | Catch | Buyers, rather than sellers, would pay the GST on plastic, electronic and tyre scrap and used cooking oil. Registered businesses would also face a 2% tax deduction at source (TDS) |
| More e-invoicing | Catch | Businesses with turnover of ₹5 crore or more would also need to e-invoice purchases from unregistered sellers and services bought from abroad |
| Old tax notices | Catch | A new clause could bring back GST notices that courts had previously struck down |
PIB, Ministry of Finance, Recommendations of the 57th Meeting of the GST Council · 8 Oct 2026
Share it
The numbers
Embed it on your site
The code carries a credit line that links back to this page. Keep it with the chart.
From the insight
GST Council backs no arrests and a 5x higher prosecution bar
Sources
- PIB, 8 October 2026, para 11.1: "complete withdrawal of arrest powers under GST by omission of section 69 of CGST Act, 2017"
- PIB, 8 October 2026, para 11.2: "The monetary threshold for prosecution to be raised from ₹1 crore to ₹5 crore"
- PIB, 8 October 2026, paras 7.2 and 7.3: "maximum general penalty ... from Rs. 25,000/- to Rs. 10,000/-"; "no notices will be issued if the tax amount involved is less than Rs. 10,000/-"
- PIB, 8 October 2026, para 6.1, Phase 1: for zero-rated supplies and inverted duty structure, "90% of the amount claimed will be sanctioned on provisional basis automatically by the system, without officer intervention"; acknowledgement "reduced from 15 days to 10 days"
- PIB, 8 October 2026, para 8.2: refund of accumulated ITC on input services under inverted duty structure "shall be available in respect of ITC availed on input services on or after 1st November, 2026"
- PIB, 8 October 2026, para 8.3: "refund of ITC on capital goods will be spread over 60 months, and shall be available in respect of ITC availed on capital goods on or after 1st April, 2027"
- PIB, 8 October 2026, para 15: "waiver of late fee on delayed filing of return ... for taxpayers with an annual turnover up to Rs. 5 crore in the preceding financial year, if the said delayed return is filed by the end of the month in which it was due"
- PIB, 8 October 2026, para 12.1: "a conveyance carrying goods can be intercepted only on specific intelligence and with the authorisation of an officer not below the rank of Joint Commissioner" and "No interception in the transit States"
- PIB, 8 October 2026, section C2, item 2: delivery services "other than courier and postal" supplied through an e-commerce operator, at a "rate of 5% without ITC for such delivery services"
- PIB, 8 October 2026, section C1, item 5: waste and scrap of plastics, electrical and electronic waste, tyres and used cooking oil under reverse charge, the recipient "shall pay tax even if supplier is under threshold"; "Tax Deducted at Source (TDS) @ 2%" on registered-to-registered supplies
- PIB, 8 October 2026, para 18.4: "extending e-invoicing to domestic supplies received from an unregistered person where the tax is payable under reverse charge mechanism, as well as to the import of services, for taxpayers having aggregate annual turnover of Rs. 5 crore and above"
- PIB, 8 October 2026, para 18.3: "introduction of a validation clause in CGST Act, 2017, for validation of notices which have been held invalid by various courts on the ground of having been issued for multiple financial years"